BAS & GST Lodgement in Bondi: What Business Owners Need to Know
Clear, practical help with GST, PAYG and activity statement due dates from a principal-led CPA public practice and registered tax agent. registered CPA public practice and tax agents in Sydney
Content reviewed and verified by Graham Chee, with FCPA-led practice at Local Knowledge, Mascot NSW. Continuous CPA Australia member since 1986. Prior career at Goldman Sachs, BNP Investment Management and Merrill Lynch.. Last reviewed October 2026. Next review scheduled for January 2027.
TL;DR
Clear, practical help with GST, PAYG and activity statement due dates from a principal-led CPA public practice and registered tax agent. [registered CPA public practice and tax agents in Sydney](https://www.sydney.accountants)
Key Takeaways
- 1. The GST threshold: A business must generally register for GST when its current or projected GST turnover reaches $75,000. The threshold is $150,000 for a non-profit organisation. Taxi and ride-sourcing operators generally need GST registration regardless of turnover. The ATO generally requires registration within 21 days after you become aware that you must register. GST turnover is based on business income, not profit, and excludes GST itself and certain other amounts.
- 2. Quarterly BAS dates: Businesses reporting quarterly generally use 28 October for July to September, 28 February for October to December, 28 April for January to March, and 28 July for April to June. Eligible clients lodging electronically through a registered agent may receive later dates for some quarters under the ATO agent program. The applicable date should be checked rather than assumed.
- 3. Monthly BAS dates: Monthly activity statements are usually due on the 21st day after the end of the reporting month. The December monthly activity statement generally has an extended due date of 21 February. Businesses with GST turnover of $20 million or more generally report GST monthly, while smaller businesses may choose monthly reporting when it better suits their records or cash flow.
- 4. PAYG withholding: If you pay employees, directors or certain contractors and withhold tax, those amounts are reported through the activity statement. The ATO generally classifies small withholders at $25,000 or less each year, medium withholders from $25,001 to $1 million, and large withholders above $1 million. Small withholders usually pay quarterly, medium withholders monthly, and large withholders follow separate payment rules set by the ATO.
- 5. PAYG instalments: PAYG instalments are prepayments towards expected income tax. The ATO may place a business or individual into the system and show either an instalment amount or an instalment rate on the activity statement. This is separate from PAYG withholding, which is tax withheld from payments to employees and other payees.
BAS and GST lodgement without the stress
A clear answer for Bondi business owners
Bondi businesses generally need to register for GST when their current or projected GST turnover reaches $75,000, then report and pay GST through monthly, quarterly or annual activity statements. A registered tax or BAS agent can check the figures, lodge with the Australian Taxation Office and help you stay on top of each due date, but your records still need to be complete and accurate.
Principal Advisor Graham Chee, FCPA, CPA, GRCP and GRCA, leads Local Knowledge Pty Ltd, a CPA public practice and registered tax agent based in Mascot. Graham is a Fellow of CPA Australia, and the practice has been principal-led since 2003, with FCPA sign-off on every file and work performed under the CPA Code of Ethics.
For a Bondi cafe near Campbell Parade, a Hall Street retailer, an Eastern Suburbs sparky or a growing startup working from home, BAS problems often begin day to day. Sales arrive through several payment platforms, supplier bills are missed, personal purchases enter the business account or payroll is processed without enough money being set aside for PAYG withholding.
We keep it simple Single Touch Payroll (STP) Phase 2 reporting obligations. We reconcile the records, check GST and payroll coding, review unusual transactions, prepare the activity statement and confirm what is due before lodgement. This provides reasonable assurance that the BAS is based on complete, supportable records; it is not a guarantee that the ATO will never ask questions.
The rules and standard dates below reflect current Australian Taxation Office guidance. ATO notices, weekends, public holidays and registered-agent concessions can change the date that applies to a particular business, so always check the due date shown in ATO Online services or confirm it with your registered agent.
Six BAS and GST points to understand
The thresholds, cycles and due dates that matter
1. The GST threshold: A business must generally register for GST when its current or projected GST turnover reaches $75,000. The threshold is $150,000 for a non-profit organisation. Taxi and ride-sourcing operators generally need GST registration regardless of turnover. The ATO generally requires registration within 21 days after you become aware that you must register. GST turnover is based on business income, not profit, and excludes GST itself and certain other amounts.
2. Quarterly BAS dates: Businesses reporting quarterly generally use 28 October for July to September, 28 February for October to December, 28 April for January to March, and 28 July for April to June. Eligible clients lodging electronically through a registered agent may receive later dates for some quarters under the ATO agent program. The applicable date should be checked rather than assumed.
3. Monthly BAS dates: Monthly activity statements are usually due on the 21st day after the end of the reporting month. The December monthly activity statement generally has an extended due date of 21 February. Businesses with GST turnover of $20 million or more generally report GST monthly, while smaller businesses may choose monthly reporting when it better suits their records or cash flow.
4. PAYG withholding: If you pay employees, directors or certain contractors and withhold tax, those amounts are reported through the activity statement. The ATO generally classifies small withholders at $25,000 or less each year, medium withholders from $25,001 to $1 million, and large withholders above $1 million. Small withholders usually pay quarterly, medium withholders monthly, and large withholders follow separate payment rules set by the ATO.
5. PAYG instalments: PAYG instalments are prepayments towards expected income tax. The ATO may place a business or individual into the system and show either an instalment amount or an instalment rate on the activity statement. This is separate from PAYG withholding, which is tax withheld from payments to employees and other payees.
6. Records support the BAS: Tax invoices, sales reports, payroll records, bank transactions and adjustment calculations need to support the lodged figures. The ATO generally requires GST records to be retained for five years. Fair Work requires employee records to be kept for seven years, and payslips must generally be provided within one working day of payday.
How BAS lodgement works in a real Bondi business
From day-to-day records to a lodged activity statement
A BAS is not simply a figure taken from the bank balance. It is a summary of GST collected, eligible GST credits, PAYG withholding, PAYG instalments and any other obligations shown on the activity statement.
Consider a busy Bondi cafe. Customers may pay at the counter, through delivery platforms or through online ordering. Payment providers can deduct fees before depositing money into the bank. If only the net bank deposit is recorded as sales, income and GST may be understated. We match sales reports to deposits, record platform fees separately and check whether GST applies to each fee and sale.
For a local tradie, the common issue is expenses. Tools, materials, fuel and subcontractor invoices may carry GST, but wages, superannuation and many bank charges do not. A bank transaction showing $110 does not prove that an $10 GST credit can be claimed strategic cash flow and tax optimisation strategies. A valid tax invoice and the correct business purpose are important.
Retail and hospitality businesses around Bondi can also have strong summer trading followed by quieter months. GST and PAYG amounts should be set aside as sales and payroll occur. This avoids treating money collected for the ATO as available day-to-day cash.
Common errors we identify and correct include:
• Claiming GST on wages, superannuation, loan repayments or private expenses. • Claiming a full GST credit where an expense is partly private. • Missing sales from delivery platforms, online stores or secondary merchant facilities. • Recording only net merchant deposits instead of gross sales and separate fees. • Claiming GST without a valid tax invoice where one is required. • Applying GST to GST-free sales or failing to apply GST to taxable sales. • Duplicating transactions imported from bank accounts and payment platforms. • Treating a loan, owner contribution or transfer between accounts as business income. • Missing GST adjustments for bad debts, returned goods, insurance settlements or asset sales. • Reporting payroll figures that do not agree with Single Touch Payroll records.
We first reconcile the balance sheet and key accounts, not just income and expenses. GST clearing accounts, PAYG withholding, wages payable, loans and bank balances should make sense before the BAS is lodged.
Directors should also keep separate obligations in view. The ATO manages BAS, GST and PAYG reporting; Fair Work Ombudsman guidance covers employee entitlements and payroll records; and the Australian Securities and Investments Commission manages company annual reviews and corporate records. An ASIC annual review is not a BAS, and completing one does not meet an ATO lodgement obligation.
Our step-by-step BAS process
A structured way to stay accurate and on time
Confirm your obligations and due dates
We check your GST basis, reporting cycle, PAYG withholding status, PAYG instalments and the due date shown by the ATO. We also consider whether turnover is approaching the $75,000 GST threshold.
Bring the records up to date
We reconcile bank accounts, sales platforms, supplier bills, payroll and key balance-sheet accounts. Missing documents and unclear transactions are listed so you know exactly what is needed.
Review and prepare the BAS
We check GST coding, compare sales and payroll reports, investigate unusual movements and prepare the activity statement. The figures and expected payment are explained in plain English before lodgement.
Lodge and plan the next cycle
Once authorised, we lodge through the registered-agent channel and confirm the amount and payment date. We then set the next document deadline and help you maintain a systematised routine for records and cash flow.
BAS questions Bondi owners commonly ask
Straight answers to practical concerns
Q.My Bondi business has reached $75,000 in sales. What should I do?
Check your current and projected GST turnover straight away. If the threshold has been reached and no exception applies, you generally need to register for GST within 21 days. Do not wait until the end of the financial year. We can review the turnover calculation, effective date and treatment of sales before the first BAS is prepared.
Q.Should I lodge BAS quarterly or monthly?
Most smaller businesses report quarterly. Businesses with GST turnover of $20 million or more generally report monthly, while smaller businesses may choose monthly reporting. Monthly reporting can suit businesses that want GST records reviewed more often, but it also means more frequent due dates. The right cycle depends on ATO requirements, record quality and cash flow.
Q.What if I cannot pay the BAS by the due date?
Lodge the BAS on time even if payment will be difficult. Late lodgement and late payment are separate issues, and the ATO may apply interest or penalties. After the correct amount is lodged, you may be able to request an ATO payment plan based on your circumstances. Approval is not guaranteed.
Q.Can I claim GST on every business expense?
No. The purchase generally needs to be connected with carrying on your business, GST must have been included, and you must hold the required evidence. Wages, superannuation, most loan principal payments and many private or GST-free purchases do not produce a GST credit. Mixed-use expenses may need to be apportioned.
Q.Can you fix BAS statements that have already been lodged?
Yes, many GST and PAYG errors can be corrected through a later activity statement or a revision, depending on the type, value and timing of the error. We review the original records, work out the correct treatment and follow the applicable ATO correction rules. Larger or older errors may need a formal revision and can involve interest or penalties.
Keep your next Bondi BAS sorted
Practical support from a principal-led registered tax practice
A clean BAS starts with clean day-to-day records. When sales, bills, payroll and bank accounts are reconciled regularly, the quarter-end work becomes clearer and cash flow is easier to plan.
Local Knowledge Pty Ltd provides BAS and GST lodgement through its CPA public practice and registered tax agent credentials. Graham Chee FCPA leads the work, with FCPA sign-off on every file. We help Bondi business owners understand what is being reported, what is payable and what needs to happen before the next due date.
Contact our team for personalised guidance if your BAS is due, your bookkeeping has fallen behind or you are unsure whether your business has reached the GST threshold.
Authority references: Australian Taxation Office guidance on registering for GST, activity statement due dates, PAYG withholding and PAYG instalments; Fair Work Ombudsman guidance on employee records and payslips; Australian Securities and Investments Commission guidance on company annual reviews and director obligations.
About the Author
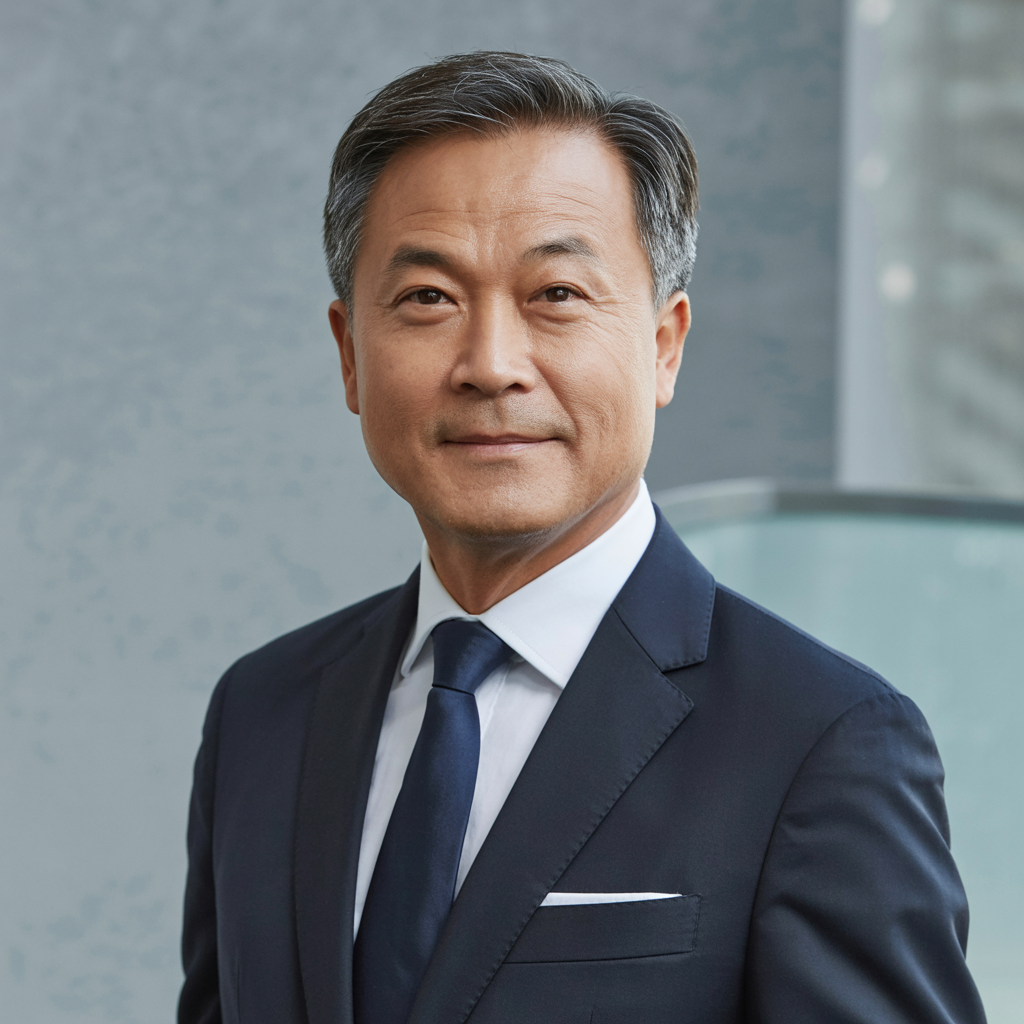
Graham Chee, FCPA, CPA, GRCP, GRCA
Principal and Founder, Local Knowledge
Graham Chee is the principal and founder of Local Knowledge, an FCPA-led Australian practice that brings institutional-grade compliance, investment-structure and intellectual-property experience directly to owner-managed businesses. Graham is a Fellow of CPA Australia (FCPA since November 2005, continuous CPA member since 1986) and holds the OCEG Governance, Risk & Compliance Professional (GRCP) and Governance, Risk & Compliance Auditor (GRCA) designations. His prior career includes senior roles at Goldman Sachs, BNP Investment Management and Merrill Lynch. Graham was previously portfolio manager of the Asian Masters Fund (IPO December 2007 – 31 December 2009), which returned +29% in AUD terms versus the MSCI Asia Pacific (ex Japan) benchmark. He signs off on 100% of client files personally.
Areas of Expertise:
Get Expert Guidance — Contact Our Team
Every business situation is different. Dates and reporting requirements can change according to ATO notices, reporting cycles, public holidays and registered-agent concessions. Seek advice for your circumstances.
Graham Chee FCPA, CPA, GRCP, GRCA · Principal, Local Knowledge · Mascot NSW · CPA-signed files