Structuring Your Chart of Accounts for Clearer BAS and Division 7A Tracking in Xero
A practical configuration guide for Sydney business owners to set up default tax codes, clearing accounts, and director loan ledgers to eliminate manual reallocations at quarter-end. streamlined bookkeeping and BAS reconciliation
Content reviewed and verified by Graham Chee, with FCPA-led practice at Local Knowledge, Mascot NSW. Continuous CPA Australia member since 1986. Prior career at Goldman Sachs, BNP Investment Management and Merrill Lynch.. Last reviewed September 2026. Next review scheduled for December 2026.
TL;DR
A practical configuration guide for Sydney business owners to set up default tax codes, clearing accounts, and director loan ledgers to eliminate manual reallocations at quarter-end. [streamlined bookkeeping and BAS reconciliation](/insights/bookkeeping-north-sydney-bookkeeping)
Key Takeaways
- Division 7A Benchmarks: Under the Income Tax Assessment Act 1936, any company money taken by a director or shareholder for private use is treated as an unfranked dividend unless repaid or placed under a compliant loan agreement by the company tax return due date. For the 2023-24 income year, the ATO benchmark interest rate is 8.27%, rising to 8.77% for the 2024-25 income year.
- Default Tax Codes: Locking in default GST settings across your operating expense and revenue accounts prevents team members or bookkeepers from picking the wrong tax rate during bank reconciliations, avoiding costly BAS errors.
- Dedicated Director Loan Ledgers: Rather than using a generic Drawings account, companies require a dedicated Non-Current Liability or Asset ledger named Director Loan - [Director Name] with Enable Payments to this Account switched on to accurately track private drawings and owner contributions.
- Point of Sale and Merchant Clearing: Square, Stripe, Tyro, and EFTPOS settlements must flow into a balance sheet clearing account so merchant processing fees and net daily payouts balance cleanly against gross takings.
- Wages and Superannuation Clearing: Under Single Touch Payroll (STP) Phase 2 and Fair Work standards, running separate liability codes for PAYG Withholding and Superannuation Payable keeps statutory debts visible and ready for quarterly lodgement without guesswork.
Clear Books, Zero Quarter-End Stress
How a clean ledger setup protects your cash flow and compliance
A properly structured Chart of Accounts in Xero separates business operating costs from shareholder drawings and establishes dedicated clearing accounts with preset GST tax codes. This setup eliminates quarter-end reallocations and guarantees an auditable trail for both your Business Activity Statement (BAS) and Australian Taxation Office (ATO) Division 7A compliance. Principal Advisor Graham Chee (FCPA, CPA) draws on Fellow CPA Australia status and prior institutional roles to deliver authority-grade guidance on practical bookkeeping workflows. When you run a busy trade business in Alexandria or a cafe in Surry Hills, having money move between your personal pocket and the company bank account is common, but mixing those up inside Xero creates pure chaos Sydney accounting specialists. When quarterly BAS due dates arrive on 28 October, 28 February, 28 April, and 28 July, you should not be spending late nights guessing whether a card swipe was for timber, coffee beans, or personal groceries. With a systematised Chart of Accounts, every single dollar has a clear home from the moment it is reconciled, keeping your day to day bookkeeping simple and completely stress-free.
Key Accounting Foundations
What you need to know about your Xero setup
Division 7A Benchmarks: Under the Income Tax Assessment Act 1936, any company money taken by a director or shareholder for private use is treated as an unfranked dividend unless repaid or placed under a compliant loan agreement by the company tax return due date. For the 2023-24 income year, the ATO benchmark interest rate is 8.27%, rising to 8.77% for the 2024-25 income year.
Default Tax Codes: Locking in default GST settings across your operating expense and revenue accounts prevents team members or bookkeepers from picking the wrong tax rate during bank reconciliations, avoiding costly BAS errors.
Dedicated Director Loan Ledgers: Rather than using a generic Drawings account, companies require a dedicated Non-Current Liability or Asset ledger named Director Loan - [Director Name] with Enable Payments to this Account switched on to accurately track private drawings and owner contributions.
Point of Sale and Merchant Clearing: Square, Stripe, Tyro, and EFTPOS settlements must flow into a balance sheet clearing account so merchant processing fees and net daily payouts balance cleanly against gross takings.
Wages and Superannuation Clearing: Under Single Touch Payroll (STP) Phase 2 and Fair Work standards, running separate liability codes for PAYG Withholding and Superannuation Payable keeps statutory debts visible and ready for quarterly lodgement without guesswork.
Quarterly BAS Alignment: Grouping accounts according to ATO reporting labels (G1 Total Sales, 1A GST on Sales, 1B GST on Purchases) ensures your Xero Activity Statement report mirrors your live bank balances perfectly.
Practical Application in Your Business
Real-world setups for suburban Sydney businesses
Consider a growing electrical business in Botany. The owner uses the company debit card at Bunnings for project materials, but also occasionally taps it for weekend family groceries or fuel for a private boat. In a default, out-of-the-box Xero setup, these personal expenses often land in General Expenses with a default GST on Expenses tax code. When BAS time comes around, the business mistakenly claims input tax credits on personal living expenses, breaching ATO rules. Furthermore, at year-end, the external tax agent must manually untangle hundreds of transactions, reallocating them into a shareholder loan. This creates an unexpected Division 7A issue where the director suddenly owes the company tens of thousands of dollars that must either be paid back with commercial interest or declared as taxable dividend income.
By contrast, our principal-led practice implements a systematised workflow. We create a clean Current Asset or Liability code (typically Account 840 or 750) titled 'Director Loan Account - [Name]' with a BAS Excluded tax code strategic cash flow and financial management. When the director pays for personal items, the transaction is coded directly to this ledger with zero GST claimed. If the director pays for business parking or trade tools using their personal credit card, an expense claim or direct payment is credited to that exact same ledger. Meanwhile, a daily clearing account is established for merchant terminals. If your shop in Marrickville takes 1,500 dollars on Saturday, the full gross amount posts to Sales with GST, the merchant fee moves to Bank Fees with GST, and the net payout clears the bank feed cleanly. Everything stays sorted day to day, giving you complete clarity over your real cash flow.
Recommended Steps to Tidy Your Ledger
A step by step approach to get your books sorted
Review Current Chart of Accounts
Export your current Xero Chart of Accounts to review every active ledger. Identify redundant codes, check that accounts match your legal structure (Pty Ltd versus Sole Trader), and archive outdated accounts to keep your ledger simple.
Configure Default Tax Codes
Set permanent default tax codes on every account. Assign 'GST on Expenses' to direct job costs and general operational overheads, 'GST Free Expenses' to water rates, bank charges, and ASIC fees, and 'BAS Excluded' to loan accounts, superannuation, and internal transfers.
Create Clearing and Loan Accounts
Set up individual director loan ledgers for each shareholder, ensuring the 'Enable Payments to this Account' toggle is selected. Establish separate clearing accounts for payroll wages, superannuation, and point-of-sale merchant providers.
Lock Periods and Reconcile Monthly
After lodging each quarterly BAS or monthly IAS, set a Xero Lock Date under Financial Settings. This stops historical transactions from being altered, preserving your reconciliations and ensuring your books match what was lodged with the ATO.
Frequently Asked Questions
Common questions Sydney business owners ask our team
Q.What is the difference between Drawings and a Director Loan in Xero?
A Drawings account is an equity ledger used by Sole Traders and Partnerships to record funds taken out by the owner. A Director Loan is an asset or liability ledger used by incorporated companies (Pty Ltd) to track money borrowed from or lent to the company by a director. Because a company is a separate legal entity, taking money out creates a Division 7A loan obligation governed by strict ATO rules.
Q.Why should clearing accounts have a zero balance at month-end?
Clearing accounts are temporary holding spaces. For example, your payroll clearing account temporarily holds net wages between the day payroll is posted and the day the bank payment clears. If your clearing account has a lingering balance at month-end, it indicates an unpaid wage, a duplicated transaction, or an uncoded bank feed entry that needs attention.
Q.Can I claim GST back on items coded to my Director Loan account?
No. Transactions coded to a Director Loan account represent personal drawings, shareholder repayments, or private funding, not business operating costs. They must always use the 'BAS Excluded' tax rate so they do not flow onto your Business Activity Statement or claim unentitled GST credits.
Q.What happens if my Director Loan is overdrawn at the end of the financial year?
If you take more money out of the company than you put in, the company has effectively lent you money. Under Division 7A, you must either repay the balance in full before the company lodges its tax return, or execute a formal Division 7A loan agreement with minimum yearly principal and interest repayments based on the ATO benchmark interest rate (8.77% for 2024-25).
Q.How do I stop staff from selecting the wrong tax codes in Xero?
Lock default tax codes directly into each account within the Chart of Accounts settings. When your team creates bills, purchase orders, or sales invoices, Xero will automatically assign the correct tax rate without requiring the user to choose manually, keeping your data entry consistent and clean.
About the Author
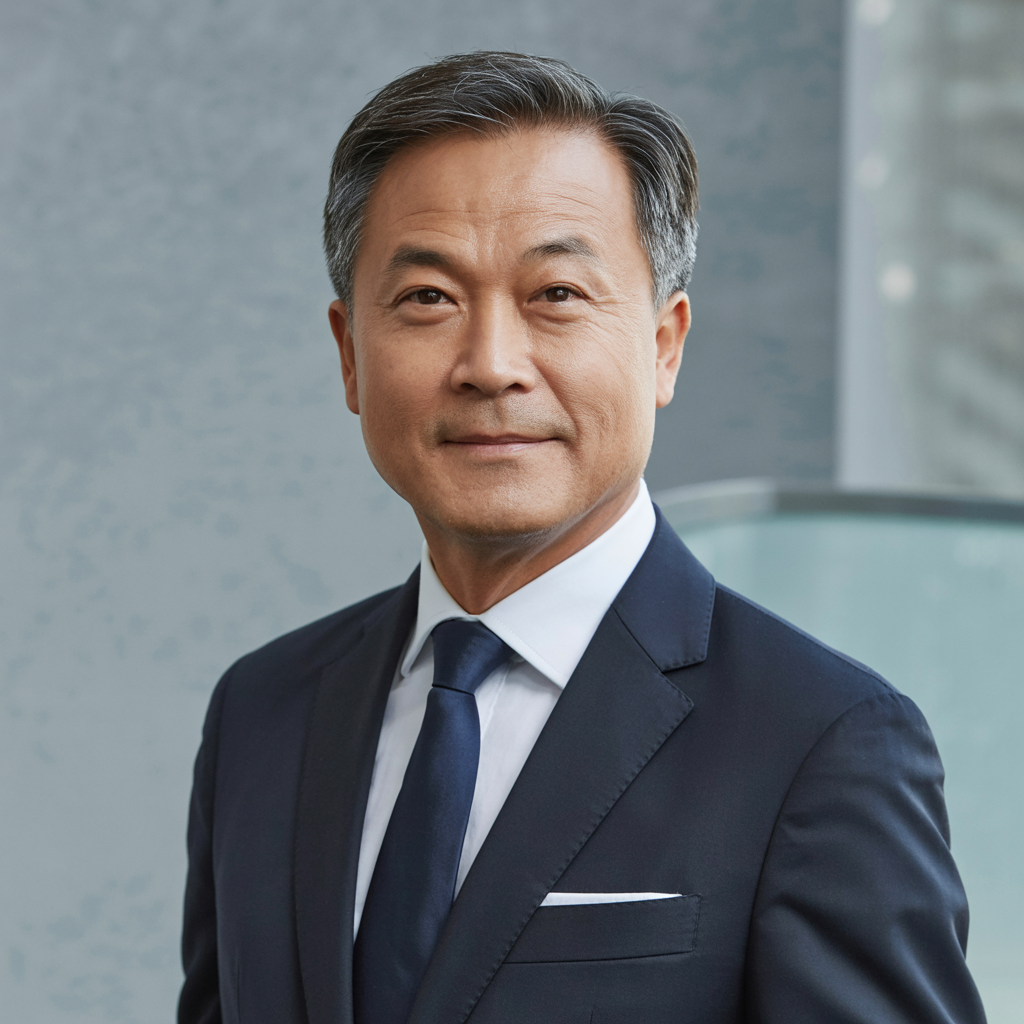
Graham Chee, FCPA, CPA, GRCP, GRCA
Principal and Founder, Local Knowledge
Graham Chee is the principal and founder of Local Knowledge, an FCPA-led Australian practice that brings institutional-grade compliance, investment-structure and intellectual-property experience directly to owner-managed businesses. Graham is a Fellow of CPA Australia (FCPA since November 2005, continuous CPA member since 1986) and holds the OCEG Governance, Risk & Compliance Professional (GRCP) and Governance, Risk & Compliance Auditor (GRCA) designations. His prior career includes senior roles at Goldman Sachs, BNP Investment Management and Merrill Lynch. Graham was previously portfolio manager of the Asian Masters Fund (IPO December 2007 – 31 December 2009), which returned +29% in AUD terms versus the MSCI Asia Pacific (ex Japan) benchmark. He signs off on 100% of client files personally.
Areas of Expertise:
Industry-specific insights
This article is especially relevant to these industries. See how we tailor our services for each.