Content reviewed and verified by Graham Chee, with FCPA-led practice at Local Knowledge, Mascot NSW. Continuous CPA Australia member since 1986. Prior career at Goldman Sachs, BNP Investment Management and Merrill Lynch.. Last reviewed September 2026. Next review scheduled for December 2026.
TL;DR
A governance-first blueprint for SME directors seeking to delegate general ledger administration to senior accounting oversight.
The Director's Dilemma: Tactical Reconciliation Versus Commercial Strategy
For Australian SME founders, the operational gravitational pull of manual recordkeeping represents one of the most persistent bottlenecks to enterprise scaling. What begins in early-stage operations as an understandable desire to control operational expenditure frequently calcifies into an administrative trap. Directors find their cognitive bandwidth consumed by tactical data entry, bank feed clearing, supplier invoice coding, and payroll runs, rather than capital allocation, commercial negotiations, and business development. Under Australian corporate law, the responsibility for maintaining accurate financial accounts rests unambiguously with the board under Section 286 of the Corporations Act 2001 (Cth) [legislation.gov.au]. However, fulfilling this legal obligation does not require the founder to act as the primary operational bookkeeper. In fact, doing so frequently compromises governance quality. When a chief executive operates inside the general ledger late at night, the business forfeits structural segregation of duties, strategic forecasting accuracy, and founder-led market expansion. Navigating the founder exit from bookkeeping requires an institutional delegation framework that transitions an SME from reactive administrative maintenance to proactive, compliant commercial intelligence.
The True Opportunity Cost: Quantifying the Drag of Founder-Led Administration
The standard rationale for maintaining in-house, founder-led bookkeeping is the perceived avoidance of external advisory overheads. From a pure accounting perspective, this assessment fails to price the enterprise value lost to operational diversion. If a founder allocates ten to fifteen hours per week to bank reconciliations, debtor chasing, and manual data validation, that investment represents forty to sixty hours per month stripped from high-leverage commercial pursuits. To stop doing your own books is not an exercise in administrative abdication; it is a clinical capital reallocation decision. The opportunity cost of founder bookkeeping in Australia is directly reflected in delayed client acquisition, deferred operational standardisation, and missed product iteration cycles. Furthermore, founder-led data entry introduces hidden financial latency. Receipts are processed weeks after payment, credit card allocations accumulate until BAS deadlines loom, and the resulting financial statements become historic post-mortems rather than forward-looking commercial instruments. By contrast, delegating financial operations SME structures ensures continuous financial record integrity while releasing executive capacity back into enterprise growth initiatives.
Governance, Risk, and Compliance: Why DIY Ledgers Threaten Director Duties
Operating without formal financial controls introduces systemic corporate exposure. Under Section 180 of the Corporations Act 2001 (Cth) [legislation.gov.au], directors owe a statutory duty of care and diligence to the enterprise, while Section 588G imposes personal liability for insolvent trading if debt commitments are incurred without reasonable grounds for expecting solvency. When SME directors maintain their own general ledgers, the risk of DIY bookkeeping for Australian directors multiplies across regulatory jurisdictions. Operational errors routinely surface: incorrect Goods and Services Tax (GST) coding on cross-border transactions, non-compliance with the Superannuation Guarantee (Administration) Act 1992 (Cth) [legislation.gov.au] regarding ordinary time earnings, and improper recognition of Division 7A benchmark interest rates under the Income Tax Assessment Act 1936 (Cth) [ato.gov.au]. Applying formal Governance, Risk, and Compliance Professional (GRCP) principles reveals that amateur financial administration eliminates the structural boundary between transactional execution and statutory oversight. When an individual executes transactions, logs journal entries, and reconciles the bank statements without independent verification, the risk of misstatement or systemic statutory non-compliance escalates significantly.
From Tactical Data Entry to Strategic Foresight: The FCPA Elevation
Establishing Internal Controls: APES 110 Compliance and Segregation of Duties
A frequent barrier preventing founders from delegating financial operations is the perceived loss of operational control and the fear of internal fraud. The institutional solution is not founder micromanagement; it is the establishment of rigorous internal financial controls governed by professional standards. When professional accountants oversee your finance function, their engagement is strictly governed by APES 110: Code of Ethics for Professional Accountants [apesb.org.au], issued by the Accounting and Professional & Ethical Standards Board (APESB). Delegating financial operations SME under APES 110 enforces foundational ethical principles: integrity, objectivity, professional competence and due care, confidentiality, and professional behaviour. Structuring a robust control environment requires implementing strict segregation of duties between operational authorization, payment execution, and reconciliation verification. Under a compliant framework, operational bookkeepers stage electronic payment files, the senior accounting practice verifies ledger alignment and statutory tax compliance, and the founding director retains final bank release authority. This triple-layer architecture completely eliminates single-point financial vulnerability while liberating the founder from routine data capture.
A Four-Stage Delegation Playbook: Exiting the General Ledger Safely
Transitioning from manual, late-night financial administration to an institutionally governed accounting architecture requires a planned, staged migration. Founders cannot abdicate overnight; they must execute a structured handover that protects corporate compliance and operational continuity. The executive finance delegation playbook for SMEs follows four clear, sequential stages:
Measuring the ROI of Strategic Delegation: Reallocating Founder Hours to Scale
The transition from manual bookkeeping to FCPA oversight Mascot or broader Sydney enterprises must ultimately be justified through measurable enterprise returns. Return on investment (ROI) in this domain manifests through two distinct vectors: direct statutory risk mitigation and commercial revenue expansion. By delegating transactional finance to an institutionally disciplined practice, directors eliminate costly year-end cleanup accounting fees, prevent ATO general interest charge (GIC) penalties, and optimize input tax credits under the A New Tax System (Goods and Services Tax) Act 1999 (Cth) [legislation.gov.au]. More significantly, freeing 40 to 60 hours of executive capacity per month permits commercial focus on high-impact initiatives: enterprise client acquisition, supply chain renegotiations, operational efficiency upgrades, and capital raising. When evaluated against the enterprise value unlocked by director-level commercial execution, the investment in senior professional financial oversight demonstrates immediate, sustained commercial dividends.
Frequently Asked Questions
Q.Does delegating bookkeeping relieve me of my statutory director responsibilities?
No. Under Section 286 and Section 180 of the Corporations Act 2001 (Cth) [legislation.gov.au], enterprise directors retain ultimate statutory responsibility for maintaining accurate books and records. Delegating bookkeeping and financial administration to a professional firm shifts operational execution and internal control management to qualified specialists, but the board retains core fiduciary oversight. Working with an FCPA ensures your accounts are governed by institutional rigor, providing reliable financial reporting that empowers you to fulfill your statutory director duties and solvency monitoring with confidence [asic.gov.au].
Q.How does professional financial delegation protect against employee fraud?
Professional delegation mitigates fraud risks by enforcing strict segregation of duties as mandated by governance frameworks and professional ethical guidelines like APES 110 [apesb.org.au]. In an unsegregated DIY environment, an internal staff member or founder might manage invoicing, payment execution, and reconciliation simultaneously. A professional accounting structure establishes independent operational silos: the bookkeeper prepares payment batches, the professional accountant validates ledger integrity, and the business owner releases the funds via banking controls [business.gov.au].
Q.What is the difference between a traditional bookkeeper and an FCPA-led advisory firm?
A standard bookkeeper focuses primarily on tactical data entry, bank feed reconciliations, and routine compliance tasks within the bounds of a BAS agent license. A Fellow of CPA Australia (FCPA) brings advanced executive expertise, institutional governance knowledge, and strategic financial advisory capabilities. Under APES 110 [apesb.org.au] and CPA Australia standards, an FCPA-led practice oversees the entire accounting architecture, ensuring balance sheet integrity, Australian Accounting Standards (AASB) compliance, strategic tax alignment, and dynamic forward-looking cash flow forecasting [cpaaustralia.com.au].
Q.How do I ensure my corporate tax returns align with my ongoing bookkeeping?
The most effective method is utilizing a unified, principal-led accounting practice where transactional recordkeeping and strategic corporate taxation are managed under one continuous workflow. When bookkeeping is disconnected from year-end tax compliance, critical adjustments—such as Division 7A loan requirements under the Income Tax Assessment Act 1936 [ato.gov.au] or capital asset depreciation under AASB 116 [aasb.gov.au]—are delayed until year-end, resulting in costly cleanup fees and distorted profit assessments.
Q.What are the common risks of DIY bookkeeping for Australian directors?
DIY bookkeeping exposes directors to severe regulatory, operational, and financial hazards. Common issues include incorrect Goods and Services Tax (GST) allocations under the GST Act [legislation.gov.au], late or inaccurate Single Touch Payroll (STP) Phase 2 reporting, and errors in calculating Superannuation Guarantee obligations. The ATO imposes personal Director Penalty Notices (DPNs) for unpaid superannuation and PAYG withholding [ato.gov.au]. Furthermore, unverified ledgers often mask cash flow insolvency risks under Section 588G of the Corporations Act 2001 [legislation.gov.au].
Q.Why should Sydney SMEs consider an outsourced finance model rather than hiring internally?
Hiring a full-time, high-caliber internal finance team introduces significant payroll overhead, recruitment friction, and single-person key-person risk. For most SMEs, hiring a junior internal bookkeeper lacks strategic depth, while an internal CFO is cost-prohibitive. An outsourced, principal-led model provides access to senior FCPA financial governance and operational execution without full-time executive overhead. This structure delivers institutional expertise, continuity of service, and strict compliance with Australian regulatory standards [business.gov.au].
Principal Perspective: Institutional Discipline for Owner-Operated Business
Throughout a career spanning institutional financial environments—including roles at Goldman Sachs, BNP Investment Management, and Merrill Lynch—the foundational lesson remains consistent: sustainable enterprise scale requires institutional systems, not heroic individual operational effort. In our multi-decade, principal-led practice at Local Knowledge in Mascot, NSW, we regularly observe ambitious founders trapped under the operational burden of transactional accounting. Founders mistakenly view manual reconciliation as exercising financial prudence, when in reality it introduces unmanaged operational risk and deprives the business of commercial leadership. Escaping manual bookkeeping is a strategic operational imperative. By implementing clear internal controls, aligning data capture with APES 110 professional standards, and subjecting the balance sheet to FCPA-level scrutiny, business owners transform their finance function from an administrative chore into a strategic commercial asset.
Transition Your Finance Function to Senior Professional Oversight
If you are an Australian business founder ready to transition your general ledger from manual administration to institutional governance, speak with our principal. Local Knowledge provides comprehensive, principal-led financial operations, corporate tax strategy, and compliance oversight to owner-operated SMEs across Sydney and Australia. Every engagement is personally reviewed and signed off by Graham Chee, FCPA, ensuring your enterprise gets its tax right and maintains absolute alignment with Australian regulatory frameworks.
About the Author
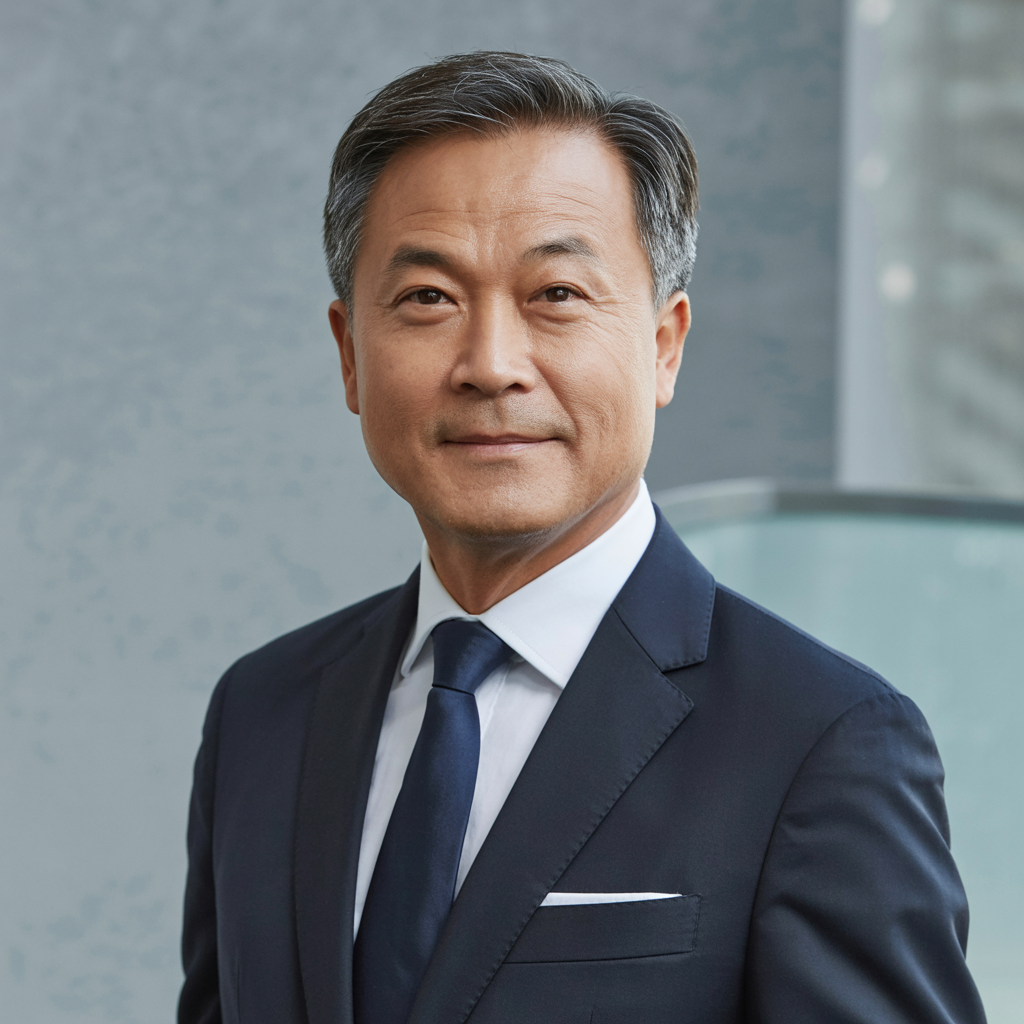
Graham Chee, FCPA, CPA, GRCP, GRCA
Principal and Founder, Local Knowledge
Graham Chee is the principal and founder of Local Knowledge, an FCPA-led Australian practice that brings institutional-grade compliance, investment-structure and intellectual-property experience directly to owner-managed businesses. Graham is a Fellow of CPA Australia (FCPA since November 2005, continuous CPA member since 1986) and holds the OCEG Governance, Risk & Compliance Professional (GRCP) and Governance, Risk & Compliance Auditor (GRCA) designations. His prior career includes senior roles at Goldman Sachs, BNP Investment Management and Merrill Lynch. Graham was previously portfolio manager of the Asian Masters Fund (IPO December 2007 – 31 December 2009), which returned +29% in AUD terms versus the MSCI Asia Pacific (ex Japan) benchmark. He signs off on 100% of client files personally.
Areas of Expertise:
Contact Us Today
General information only. Speak to us for advice specific to your situation. Every file is signed off by our principal under CPA Code of Ethics.
Graham Chee FCPA, CPA, GRCP, GRCA · Principal, Local Knowledge · Mascot NSW · CPA-signed files