Structuring for Scale: Navigating Trust and Company Hybrid Models for Sydney Businesses Targeting Regional NSW Expansion
A principal-led analysis of asset protection, entity design, and NSW state tax friction when expanding from the metropolitan market into regional hubs. tax-efficient corporate and trust design
Content reviewed and verified by Graham Chee, with FCPA-led practice at Local Knowledge, Mascot NSW. Continuous CPA Australia member since 1986. Prior career at Goldman Sachs, BNP Investment Management and Merrill Lynch.. Last reviewed September 2026. Next review scheduled for December 2026.
TL;DR
A principal-led analysis of asset protection, entity design, and NSW state tax friction when expanding from the metropolitan market into regional hubs. [tax-efficient corporate and trust design](/insights/business-structure-tax-efficiency)
Key Takeaways
- Isolation of Balance Sheet Assets: Established Sydney commercial property and proprietary technology must remain divorced from regional operational entities. Deploying a trading company owned by a discretionary family trust or holding vehicle ensures operational liabilities in regional yards, sites, or transit corridors cannot contaminate Sydney-held balance sheet equity.
- Revenue NSW Payroll Tax Grouping Rules: Expanding headcounts into regional NSW often catches directors unprepared for statutory grouping under Part 5 of the Payroll Tax Act 2007 (NSW). Even if regional entities operate under distinct trading names or regional directors, common control provisions combine payrolls against the NSW annual threshold of $1,200,000, taxed at 5.45 percent.
- Corporate Beneficiary and Division 7A Friction: Retaining capital within a regional corporate vehicle to fund plant, fleet, and regional leases at the 25 percent base rate entity tax rate requires meticulous loan agreement governance under Division 7A of the Income Tax Assessment Act 1936 to prevent unfranked deemed dividends.
- Preservation of the CGT Concession: Running operations entirely through a standard corporate structure strips the 50 percent general CGT discount under Division 115 of the ITAA 1997 upon eventual exit. A trust holding shares in the regional trading subsidiary ensures capital appreciation yields an optimal after-tax outcome for shareholders.
- Land Tax Surcharges and NSW Thresholds: Acquiring regional commercial premises through discretionary trusts triggers the NSW land tax surcharge and absence of the tax-free threshold ($1,075,000 for the 2024 land tax year) unless the trust deed is explicitly structured or a unit trust is leveraged with precision under Revenue NSW guidelines.
The Strategic Stakes of Geographic Expansion
Balancing metropolitan equity with regional operating exposure
A hybrid trust and corporate model allows Sydney enterprises to ring-fence valuable metropolitan intellectual property and balance sheet equity while isolating the operational, industrial, and site risks of regional expansion. By deploying a corporate operating subsidiary owned by a discretionary or unitised trust, directors retain the 25 percent base rate corporate tax cap on retained working capital while preserving the 50 percent capital gains tax discount on ultimate asset succession. The real question is whether your existing corporate architecture can absorb regional operational volatility without dragging Sydney assets into the line of fire.
This analysis is written by Graham Chee, FCPA, CPA — Fellow of CPA Australia since November 2005, continuous CPA member since 1986, and principal of Local Knowledge, a principal-led practice in Mascot NSW established in 2003 commercial debt and regional growth financing. When a Sydney business headquartered in the CBD, North Sydney, or South Sydney moves capital into regions such as the Central West, Hunter, or Riverina, entity design dictates both downside risk and ultimate after-tax returns. Moving across geographic footprints inside New South Wales is not merely an operational deployment; it is a structural event that triggers critical tax thresholds under Revenue NSW, statutory director duties under the Corporations Act 2001, and cross-entity compliance obligations overseen by the ATO.
Key Structural Considerations
Navigating statutory thresholds, asset isolation, and state tax exposure
Isolation of Balance Sheet Assets: Established Sydney commercial property and proprietary technology must remain divorced from regional operational entities. Deploying a trading company owned by a discretionary family trust or holding vehicle ensures operational liabilities in regional yards, sites, or transit corridors cannot contaminate Sydney-held balance sheet equity.
Revenue NSW Payroll Tax Grouping Rules: Expanding headcounts into regional NSW often catches directors unprepared for statutory grouping under Part 5 of the Payroll Tax Act 2007 (NSW). Even if regional entities operate under distinct trading names or regional directors, common control provisions combine payrolls against the NSW annual threshold of $1,200,000, taxed at 5.45 percent.
Corporate Beneficiary and Division 7A Friction: Retaining capital within a regional corporate vehicle to fund plant, fleet, and regional leases at the 25 percent base rate entity tax rate requires meticulous loan agreement governance under Division 7A of the Income Tax Assessment Act 1936 to prevent unfranked deemed dividends.
Preservation of the CGT Concession: Running operations entirely through a standard corporate structure strips the 50 percent general CGT discount under Division 115 of the ITAA 1997 upon eventual exit. A trust holding shares in the regional trading subsidiary ensures capital appreciation yields an optimal after-tax outcome for shareholders.
Land Tax Surcharges and NSW Thresholds: Acquiring regional commercial premises through discretionary trusts triggers the NSW land tax surcharge and absence of the tax-free threshold ($1,075,000 for the 2024 land tax year) unless the trust deed is explicitly structured or a unit trust is leveraged with precision under Revenue NSW guidelines.
Practical Application in Regional Deployments
Designing the corporate operating and holding vehicle interface
Consider a premium logistics, civil engineering, or professional consultancy based in Mascot or North Sydney seeking to capitalise on major infrastructure programs across regional New South Wales. Rushing into regional contracts using the primary Sydney company exposes twenty years of built-up retained profits and capital assets to untested regional subcontractor defaults, plant liabilities, and Fair Work operational claims.
Under an advisory-grade hybrid architecture, the Sydney principal retains the existing head entity as an asset and IP holding vehicle. A newly incorporated regional operating company (OpCo) is created to sign local contracts, employ regional personnel, and lease local premises. The shares of this OpCo are held by a discretionary family trust or unit trust, with corporate beneficiaries positioned to sweep profits at the 25 percent base rate entity corporate rate when turnover sits under the $50 million threshold capital deployment and cash flow strategies. Plant and machinery deployed to regional depots can be purchased via an asset leasing trust or financing entity, leasing equipment to OpCo on commercial terms registered on the Personal Property Securities Register (PPSR). This structure isolates the Sydney parent from operational litigation while preserving clear succession, intercompany debt transparency, and tax efficiency.
The Strategic Implementation Roadmap
Four disciplined phases to execute regional entity design
Exposure and Asset Audit
Quantify your current Sydney balance sheet assets, unencumbered real property, intellectual property, and existing payroll tax thresholds under Revenue NSW regulations.
Entity Design and Grouping Review
Model the capital structure using an OpCo-HoldCo hybrid architecture, identifying control mechanisms to address corporate law compliance and Division 7A obligations.
Intercompany and PPSR Governance
Establish commercial service agreements, IP licensing arrangements, and security interests registered on the PPSR to insulate capital equipment from trading liabilities.
Periodic Statutory Realignment
Conduct annual principal-led reviews of trust distributions, Section 100A ATO compliance, and multi-entity transfer pricing before cross-border balance sheet consolidation.
Frequently Asked Questions
Boardroom inquiries on hybrid structuring and regional expansion
Q.Why not simply run the regional NSW branch through our existing Sydney operating company?
Operating through a single entity exposes all established Sydney balance sheet equity, accumulated profits, and real property to regional operational liabilities. A regional trading dispute, industrial claim, or subcontractor litigation could compromise the entire enterprise rather than remaining contained within an isolated subsidiary.
Q.How does NSW payroll tax apply when establishing a separate regional entity?
Under Part 5 of the Payroll Tax Act 2007 (NSW), businesses with common control or shared administrative and managerial connections are grouped automatically. The grouping rules pool all Australian taxable wages against the single NSW threshold of $1,200,000, meaning your regional workforce will likely be taxed at 5.45 percent from the first dollar paid.
Q.What is the primary tax friction when moving capital between a Sydney holding entity and a regional operating entity?
The primary friction stems from Division 7A of the ITAA 1936. Capital advances from a corporate beneficiary or private company to an operational entity must either be formal commercial arm's-length investments, equity subscriptions, or governed by complying loan agreements with statutory interest rates and strict seven-year or twenty-five-year terms.
Q.Does a hybrid structure protect our eligibility for the 50 percent CGT discount on sale?
Yes. If an operating business is owned directly by a holding company, the eventual sale of shares by that company does not receive the 50 percent CGT general discount under Division 115. Holding the operating company shares within a trust allows the capital gain on an eventual enterprise sale to flow through to individual beneficiaries, accessing relevant CGT concessions.
About the Author
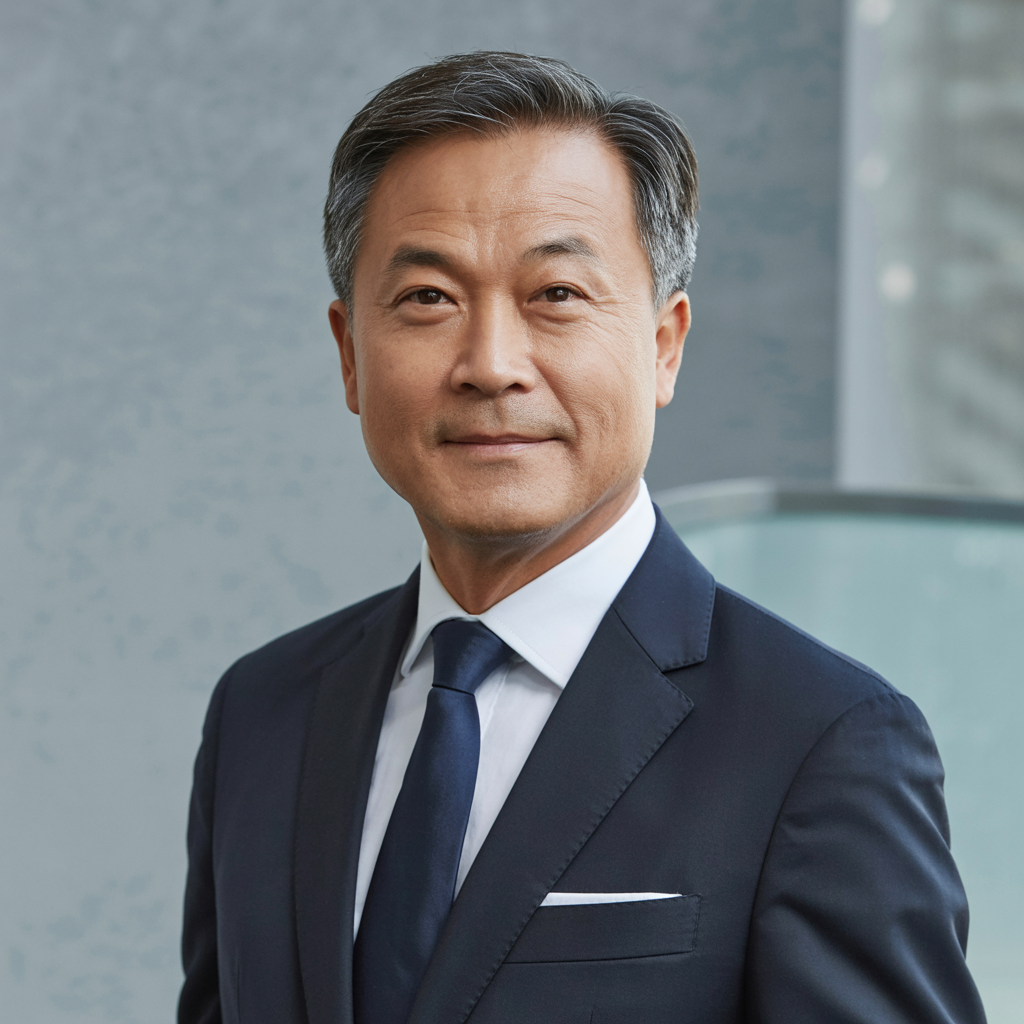
Graham Chee, FCPA, CPA, GRCP, GRCA
Principal and Founder, Local Knowledge
Graham Chee is the principal and founder of Local Knowledge, an FCPA-led Australian practice that brings institutional-grade compliance, investment-structure and intellectual-property experience directly to owner-managed businesses. Graham is a Fellow of CPA Australia (FCPA since November 2005, continuous CPA member since 1986) and holds the OCEG Governance, Risk & Compliance Professional (GRCP) and Governance, Risk & Compliance Auditor (GRCA) designations. His prior career includes senior roles at Goldman Sachs, BNP Investment Management and Merrill Lynch. Graham was previously portfolio manager of the Asian Masters Fund (IPO December 2007 – 31 December 2009), which returned +29% in AUD terms versus the MSCI Asia Pacific (ex Japan) benchmark. He signs off on 100% of client files personally.
Areas of Expertise:
Industry-specific insights
This article is especially relevant to these industries. See how we tailor our services for each.
Get Expert Guidance - Speak with an Advisor
Every corporate structure demands tailored analysis under Australian tax law. Consult an FCPA-accredited advisor before restructuring.
Graham Chee FCPA, CPA, GRCP, GRCA · Principal, Local Knowledge · Mascot NSW · CPA-signed files