Content reviewed and verified by Graham Chee, with FCPA-led practice at Local Knowledge, Mascot NSW. Continuous CPA Australia member since 1986. Prior career at Goldman Sachs, BNP Investment Management and Merrill Lynch.. Last reviewed September 2026. Next review scheduled for December 2026.
TL;DR
A deal-grade blueprint for Australian scale-up founders to bypass bureaucratic friction, lock in regulatory runway, and scale internationally without active operational drag.
Key Takeaways
- Regulatory Arbitrage and Licensing Grandfathering: Purchasing an inactive entity holding grandfathered permissions under statutory regimes, such as an Australian Financial Services Licence (AFSL) under Section 911A of the Corporations Act 2001 or specific cross-border trading exemptions, eliminates years of direct agency queues.
- AASB 3 versus Asset Acquisition Classification: Under AASB 3 Business Combinations, an acquired entity must possess inputs and substantive processes to be accounted for as a business. A non-operating corporate shell is generally accounted for as an asset acquisition, avoiding the recognition of speculative goodwill and preserving clean balance sheet equity.
- Banking Rails and Credit Vintage: Inactive corporate entities with clean corporate registries and multi-year credit histories sidestep the modern onboarding friction of Tier 1 banking systems, enabling rapid capital deployment and institutional treasury operations.
- Tax Loss Ring-Fencing and Integrity Boundaries: Under ATO tax legislation (Division 165 of the ITAA 1997), utilizing carried-forward revenue losses requires passing the Continuity of Ownership Test (COT) or the Business Continuity Test (BCT). In a phantom acquisition, revenue losses are rarely the prize; the strategic focus remains structural market access and legal asset rights.
- Elimination of Legacy Operational Drag: Unlike standard mergers and acquisitions, targeting a non-operating shell excludes Fair Work transfer-of-business liabilities (Part 2-8 of the Fair Work Act 2009), operational lease commitments, and complex employee redundancy liabilities.
The Strategic Fast-Track: Shell Acquisitions vs Greenfields
Preserving runway while buying regulatory time
Acquiring a clean, non-operating shell entity allows high-growth ventures to secure critical regulatory status, grandfathered operating licences, and immediate banking access without inheriting the burn rate, legacy headcount, or integration friction of an active business. For Australian scale-ups expanding cross-border or pivoting domestically, this transactional route converts eighteen months of bureaucratic licensing delay into an immediate six-week corporate close. Graham Chee, FCPA, CPA, principal of Local Knowledge, writes from a practice that pairs FCPA-grade compliance with Goldman Sachs, BNP Investment Management and Merrill Lynch institutional experience on cross-border structuring, growth financial strategy, capital raising readiness, and intangible-asset acquisitions.
In ecosystems like Sydney's Tech Central and Silicon Harbour, capital efficiency determines venture survival corporate restructuring and tax optimization framework. When expanding into heavily regulated verticals or secondary jurisdictions, building a greenfield entity from scratch consumes vital runway while waiting on statutory approvals from regulatory bodies. A strategic phantom target acquisition is not about tax avoidance; it is an aggressive, principal-led capital allocation decision designed to exploit regulatory arbitrage, secure institutional credibility, and defend enterprise valuation.
Core Deal Mechanics and Arbitrage Vectors
Five pillars that define successful corporate shell strategies
Regulatory Arbitrage and Licensing Grandfathering: Purchasing an inactive entity holding grandfathered permissions under statutory regimes, such as an Australian Financial Services Licence (AFSL) under Section 911A of the Corporations Act 2001 or specific cross-border trading exemptions, eliminates years of direct agency queues.
AASB 3 versus Asset Acquisition Classification: Under AASB 3 Business Combinations, an acquired entity must possess inputs and substantive processes to be accounted for as a business. A non-operating corporate shell is generally accounted for as an asset acquisition, avoiding the recognition of speculative goodwill and preserving clean balance sheet equity.
Banking Rails and Credit Vintage: Inactive corporate entities with clean corporate registries and multi-year credit histories sidestep the modern onboarding friction of Tier 1 banking systems, enabling rapid capital deployment and institutional treasury operations.
Tax Loss Ring-Fencing and Integrity Boundaries: Under ATO tax legislation (Division 165 of the ITAA 1997), utilizing carried-forward revenue losses requires passing the Continuity of Ownership Test (COT) or the Business Continuity Test (BCT). In a phantom acquisition, revenue losses are rarely the prize; the strategic focus remains structural market access and legal asset rights.
Elimination of Legacy Operational Drag: Unlike standard mergers and acquisitions, targeting a non-operating shell excludes Fair Work transfer-of-business liabilities (Part 2-8 of the Fair Work Act 2009), operational lease commitments, and complex employee redundancy liabilities.
Practical Application: Navigating the Transaction
Balancing valuation upside against deep corporate liabilities
In practice, executing a phantom target acquisition demands institutional-grade due diligence. The primary commercial appeal is speed: an Australian enterprise SaaS or fintech platform seeking cross-border expansion can spend upwards of 12 to 18 months securing direct licensing, commercial credit arrangements, and jurisdictional standing. Acquiring a dormant shell with existing regulatory pre-clearance cuts that runway drain down to the duration of legal due diligence and standard statutory notifications.
However, the commercial risks are asymmetric. When you acquire 100 percent of the issued shares in a dormant target, you inherit its entire statutory history under ASIC records or foreign corporate registries venture-backed scale-up investment strategies. Undisclosed payroll tax obligations, historic Fair Work compliance gaps, latent contract breaches, or unlodged fringe benefits tax returns follow the corporate veil. A systematised legal and financial audit must verify historical solvency, confirm the complete absence of historical environmental or director-related liabilities, and execute strict vendor indemnities backed by institutional warranty escrows.
The Strategic Acquisition Roadmap
A structured execution process for scale-up boards
Forensic Cleanliness Audit
Inspect corporate registries, ASIC filings, ATO integrated client accounts, and historic general ledgers to establish that the dormant shell carries zero contingent liabilities or active legal claims.
Statutory Authority Alignment
Evaluate regulatory pre-requisites to ensure that the change of ultimate holding company control does not trigger mandatory licence revocation under governing statutory frameworks.
Transaction Structuring and Accounting Allocation
Structure the share purchase agreement under an asset acquisition framework compliant with AASB 3, allocating purchase price directly to identifiable intangible assets and permits.
Post-Close Integration and Governance
Install principal-led corporate governance, update statutory director and secretary registers, re-establish Tier 1 banking mandates, and deploy scale-up operations.
Frequently Asked Questions
Critical insights for venture leaders and corporate boards
Q.Why acquire a non-operating corporate shell instead of an operational business?
Acquiring an active business brings legacy operational culture, unexpected burn rates, software migrations, redundant staffing, and complicated Fair Work transition provisions. A dormant shell delivers purely the regulatory access, licensures, or geographical presence you require, keeping integration burn near zero. rigorous Australian valuation methodologies
Q.Can our venture use historical tax losses contained within the acquired shell?
ATO rules under the Income Tax Assessment Act 1997 strictly regulate loss utilisation. If ownership changes by more than 50 percent, you must satisfy the Business Continuity Test. Because non-operating shells have ceased active business, claiming historical tax losses is rarely permissible, and founders should not treat historic losses as an acquisition asset. strategic financial innovation and capital structuring
Q.How does AASB 3 treat the acquisition of a dormant shell?
Under AASB 3, an entity must have inputs and applied processes capable of creating outputs to qualify as a business. Because a dormant shell lacks operational processes, the transaction is accounted for as a direct asset purchase. This means you do not record goodwill on the balance sheet, keeping your post-deal capitalization clean.
Q.What is the biggest operational risk of this strategy?
The biggest risk is inheriting historical off-balance-sheet liabilities. Even if an entity has been inactive for years, past compliance failures with statutory authorities, tax bodies, or unrecorded third-party contracts remain within the legal entity. Forensic balance sheet due diligence and comprehensive vendor warranties are non-negotiable.
About the Author
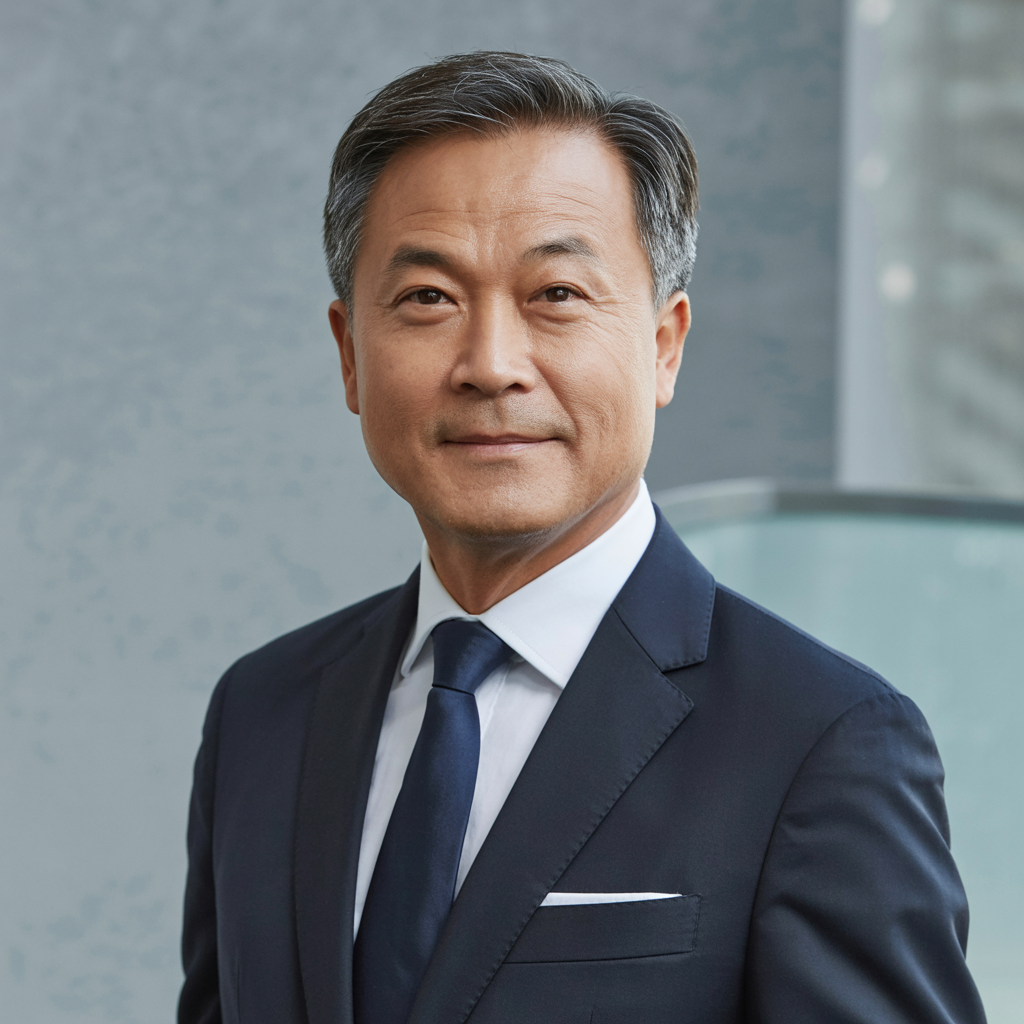
Graham Chee, FCPA, CPA, GRCP, GRCA
Principal and Founder, Local Knowledge
Graham Chee is the principal and founder of Local Knowledge, an FCPA-led Australian practice that brings institutional-grade compliance, investment-structure and intellectual-property experience directly to owner-managed businesses. Graham is a Fellow of CPA Australia (FCPA since November 2005, continuous CPA member since 1986) and holds the OCEG Governance, Risk & Compliance Professional (GRCP) and Governance, Risk & Compliance Auditor (GRCA) designations. His prior career includes senior roles at Goldman Sachs, BNP Investment Management and Merrill Lynch. Graham was previously portfolio manager of the Asian Masters Fund (IPO December 2007 – 31 December 2009), which returned +29% in AUD terms versus the MSCI Asia Pacific (ex Japan) benchmark. He signs off on 100% of client files personally.
Areas of Expertise:
Get Expert Guidance on Scale-Up Structuring
The material presented in this article is educational in nature and does not constitute formal tax, legal, or corporate financial advice. Founders and directors must seek individual counsel regarding their unique legal and operational circumstances.
Graham Chee FCPA, CPA, GRCP, GRCA · Principal, Local Knowledge · Mascot NSW · CPA-signed files